

Probability theory's vocabulary grew out of experimental work, often carried out in the laboratory, as reflected in the standard term random experiment. A random experiment is any action performed or question asked whose outcome or answer cannot be determined a priori. Ω generally denotes all the possible outcomes or answers when such a random experiment is performed. These outcomes may be numerical or non-numerical. Numerical outcomes may form a finite, countably infinite or even continuous collection.
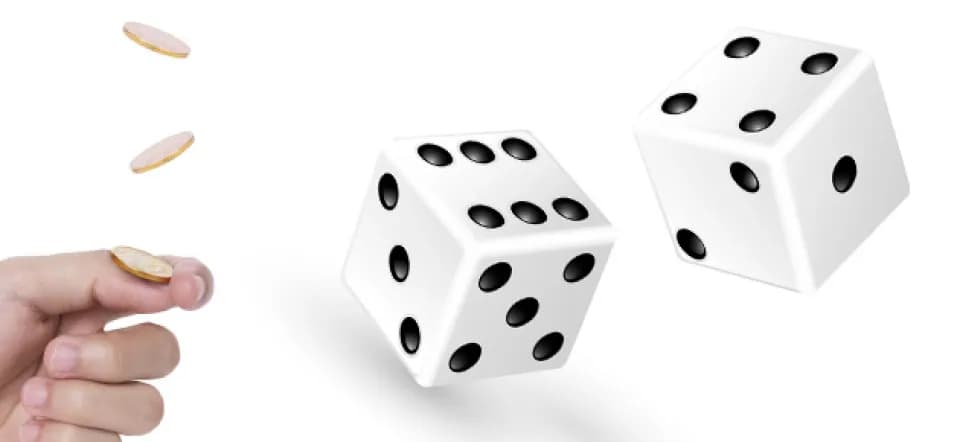
A few examples will make this clearer. To stay with familiar examples, tossing a coin gives Ω = {heads, tails}. For the roll of an ordinary die, it is fairly intuitive to take the six possible outcomes, defining Ω = {1, 2, 3, 4, 5, 6}. By contrast, if we wish to consider the number of road accidents involving bodily injury that will occur in France over the course of a year, that number will necessarily be a natural number but cannot a priori be bounded above. We can therefore take Ω to be the set of natural numbers, bearing in mind that very large numbers (or numbers close to zero) are unlikely. Similarly, to determine the duration in seconds of a train journey from Brussels to Paris, we take a realistic interval of the real line: Ω = [4,800, 7,200]. Every value in this interval is possible.
When the expected outcomes are non-numerical, we often use a random variable, which assigns a number to each possible outcome. Formally, a random variable is therefore a map from Ω to ℝ. For random experiments with numerical outcomes, the random variable often—but not always—coincides with the identity function.
One number for each possible outcome
------------------------------------
To assign probabilities when Ω is finite (or countable, meaning that it consists of a sequence of numbers), we need only associate with each possible outcome—that is, each element of Ω—a number expressing the percentage chance of observing that outcome.